

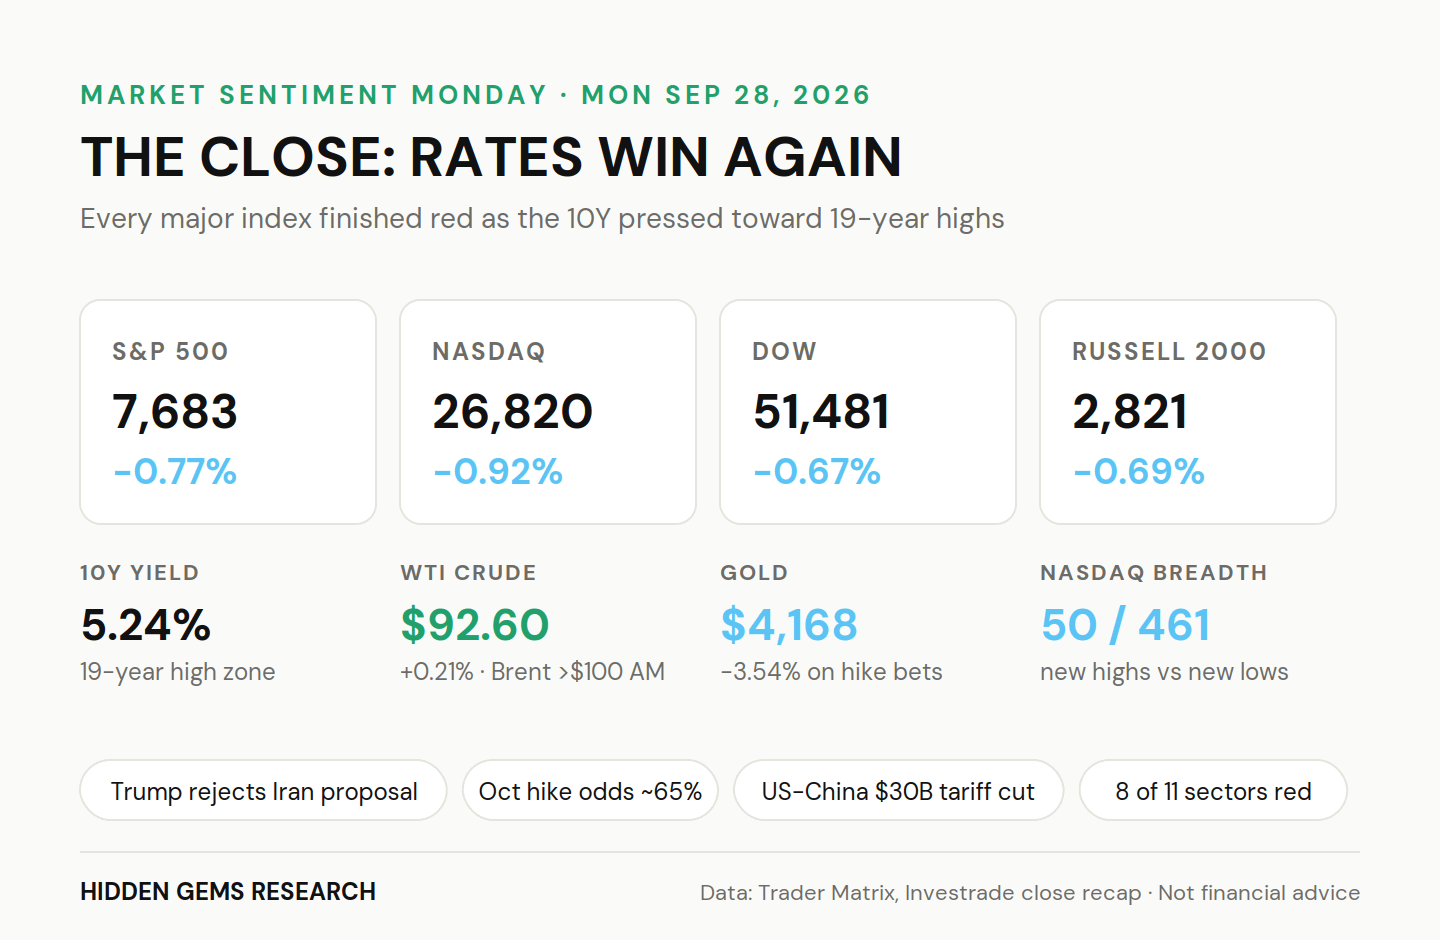
I’m excited to add Market Sentiment Monday to the weekly rotation of our content. We have more new recurring segments to follow every day this week. With the introductions out of the way, lets get into the state of the market! Rate decisions ran the market today as we creep closer to midterms. The 10Y closed at 5.24%, a 19-year high zone, and FedWatch now puts the odds of an October hike near 65%. The S&P 500 fell 0.77% to 7,683, the Nasdaq lost 0.92%, the Dow gave up 0.67% and the Russell 2000 dropped 0.69%. Eight of 11 sectors finished red. Nasdaq printed 50 new highs against 461 new lows.
THE PULSE
Futures opened the week lower last night after Trump rejected Iran’s peace proposal over the weekend. Brent pushed back above $106 in the morning and WTI traded near $96 before sellers took it back to $92.60 by the close. The 2Y led the move in yields, which is how traders price a hike: front end first. Gold fell 3.5% on the same repricing and the dollar sat near a two-month high.
Goldman flagged S&P breadth at its weakest level since the dot-com bubble. A handful of AI names are holding the index up while the rest of the market leaks. You saw it in the new-lows count today.
The gamma map from our partners at Trader Matrix frames the next few sessions. SPY closed Friday right on its gamma flip near 771 and opened below it this morning. Below the flip, dealers amplify moves, and the put wall sits near 761. QQQ sits in a tighter box between a put wall near 730 and a call wall near 745.
SECTOR ROTATION
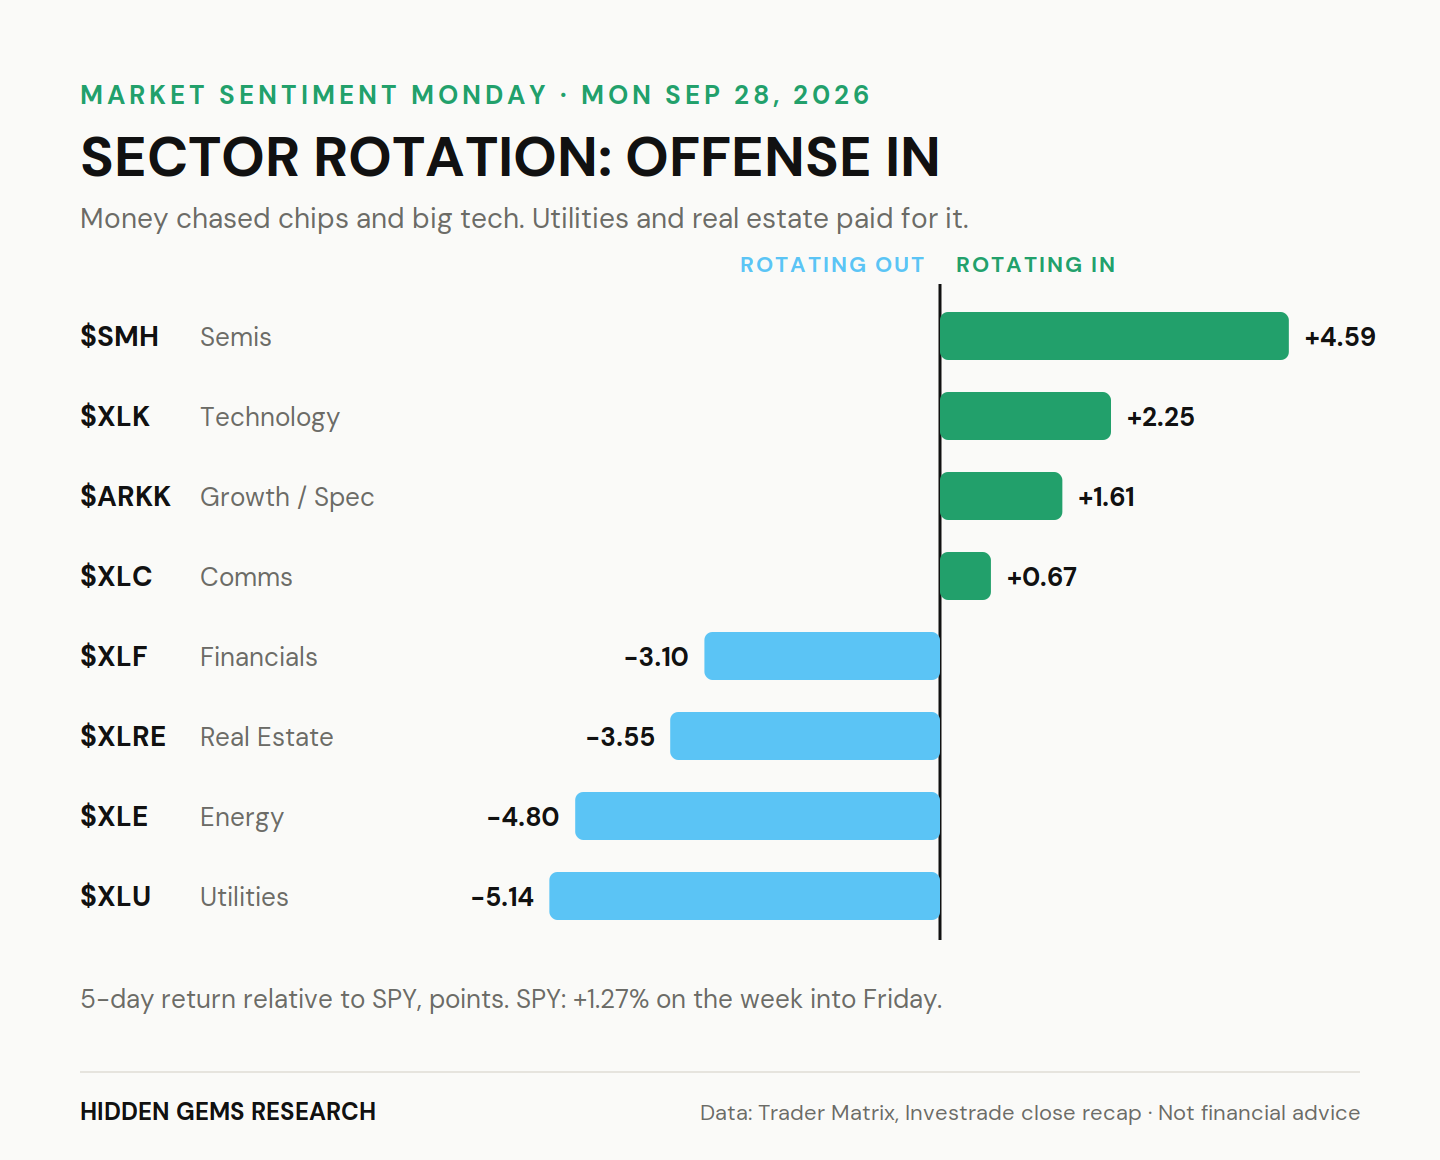
Over the past five sessions, money went into $SMH (+4.59% vs SPY) and $XLK (+2.25%). It came out of $XLU (-5.14%), $XLE (-4.80%), $XLRE (-3.55%) and $XLF (-3.10%). Utilities and real estate trade like bonds, so a 5%+ 10Y punishes them first.
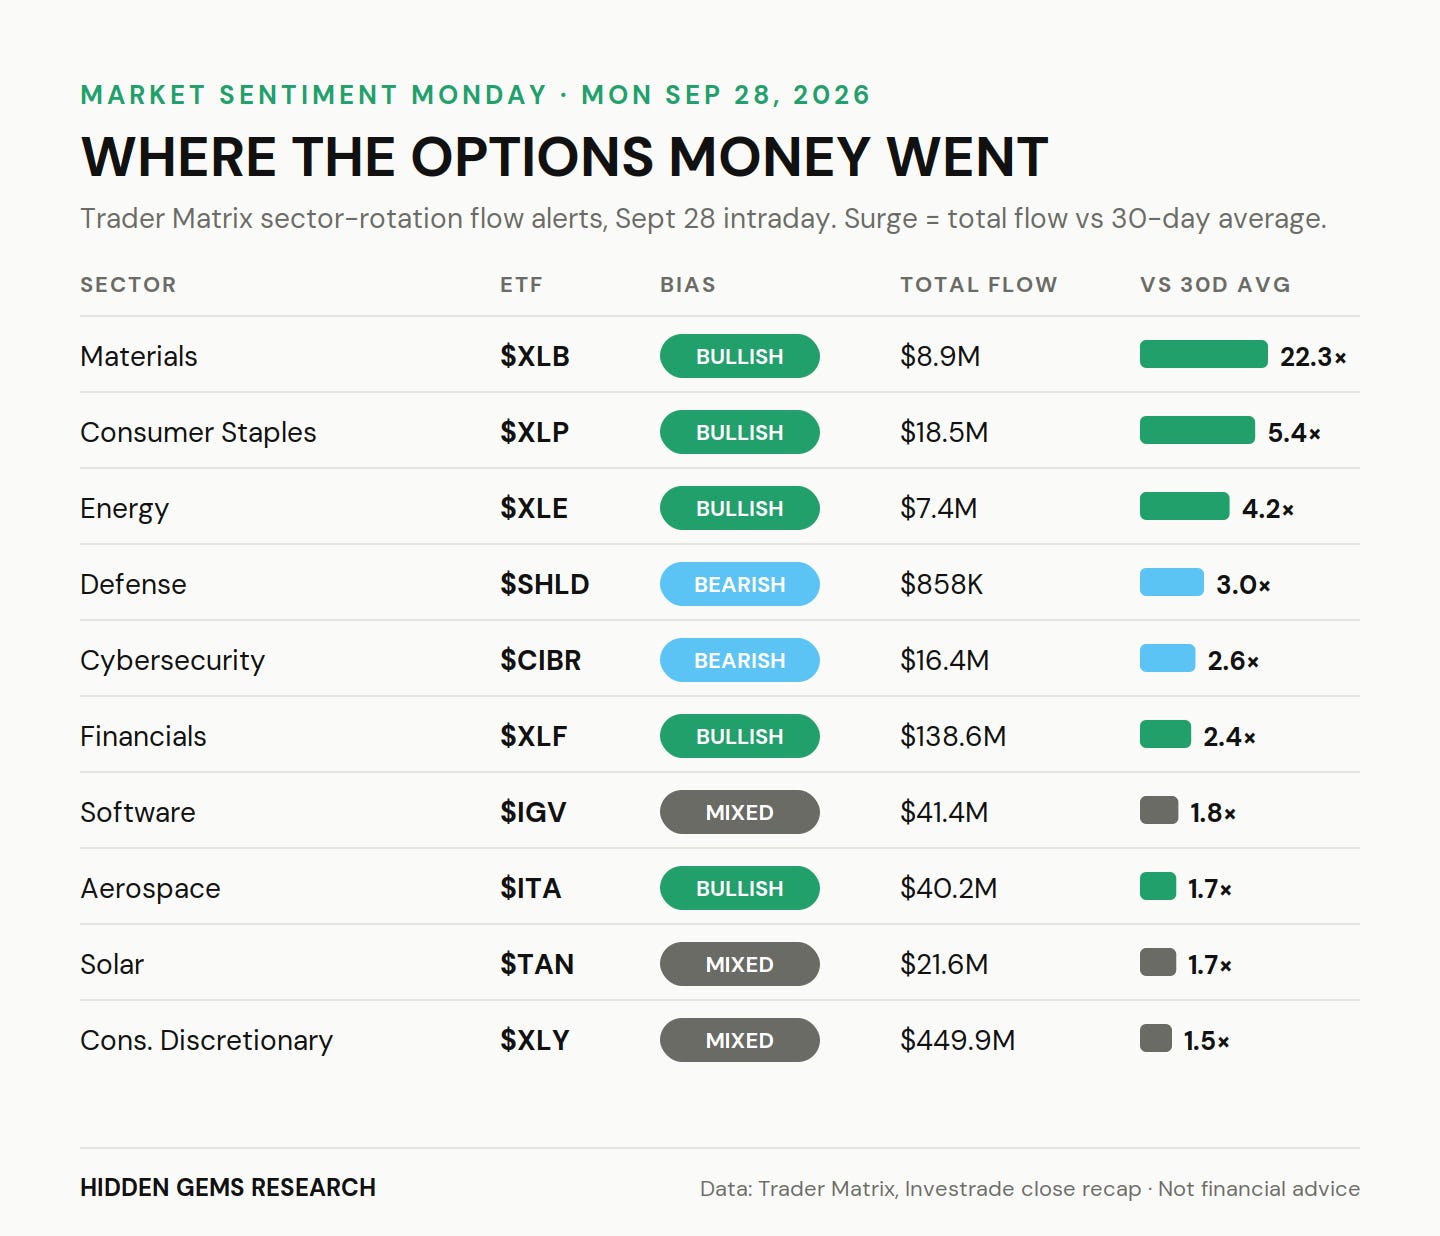
The options chain told a different story today. TM flow alerts showed bullish surges in Materials ($XLB, 22x its 30-day average), Consumer Staples ($XLP, 5.4x), Energy ($XLE, 4.2x) and Financials ($XLF, $139M in total flow). Traders bought bearish exposure in Cybersecurity ($CIBR, $10.7M bearish vs $3.3M bullish) and Defense ($SHLD). Software and Consumer Discretionary came in mixed.
The five-day chart leans offensive. Today’s flow says traders are hedging that offense with staples, materials and energy. Energy finished the week as the second-worst sector and just caught a fresh oil bid. If oil holds above $90, $XLE is the first laggard in line to turn.
MACRO AND GEOPOLITICS
Iran whipsawed oil all day. At 11:30 AM ET, a U.S. official said Trump would ease sanctions and unfreeze assets for nuclear progress, and crude sold off. At 12:18 PM, Saudi media reported Iran agreed to halt enrichment. By 3:25 PM, Iranian state media called that report false, and an Iranian security official said Hormuz, not the nuclear file, now sits at the center of talks. Bloomberg reported Iranian officials doubt a deal lands before the November 3 midterms.
Saudi Arabia restarted exports on its East-West pipeline, which routes crude around Hormuz. CENTCOM rejected Iran’s claim that it controls the strait. NBC reported eight Marines were wounded on September 14 when an Iranian cruise missile hit their ship in the strait.
The U.S. and China agreed to cut tariffs on $30B of goods each after the Trump-Xi summit. Trump announced an $18B steel plant in Iowa and said the White House is still weighing a diesel export ban, with diesel at $6.53 a gallon. In Europe, Russia struck Kyiv’s National Academy of Sciences and a Russian drone came down near the Polish border.
