

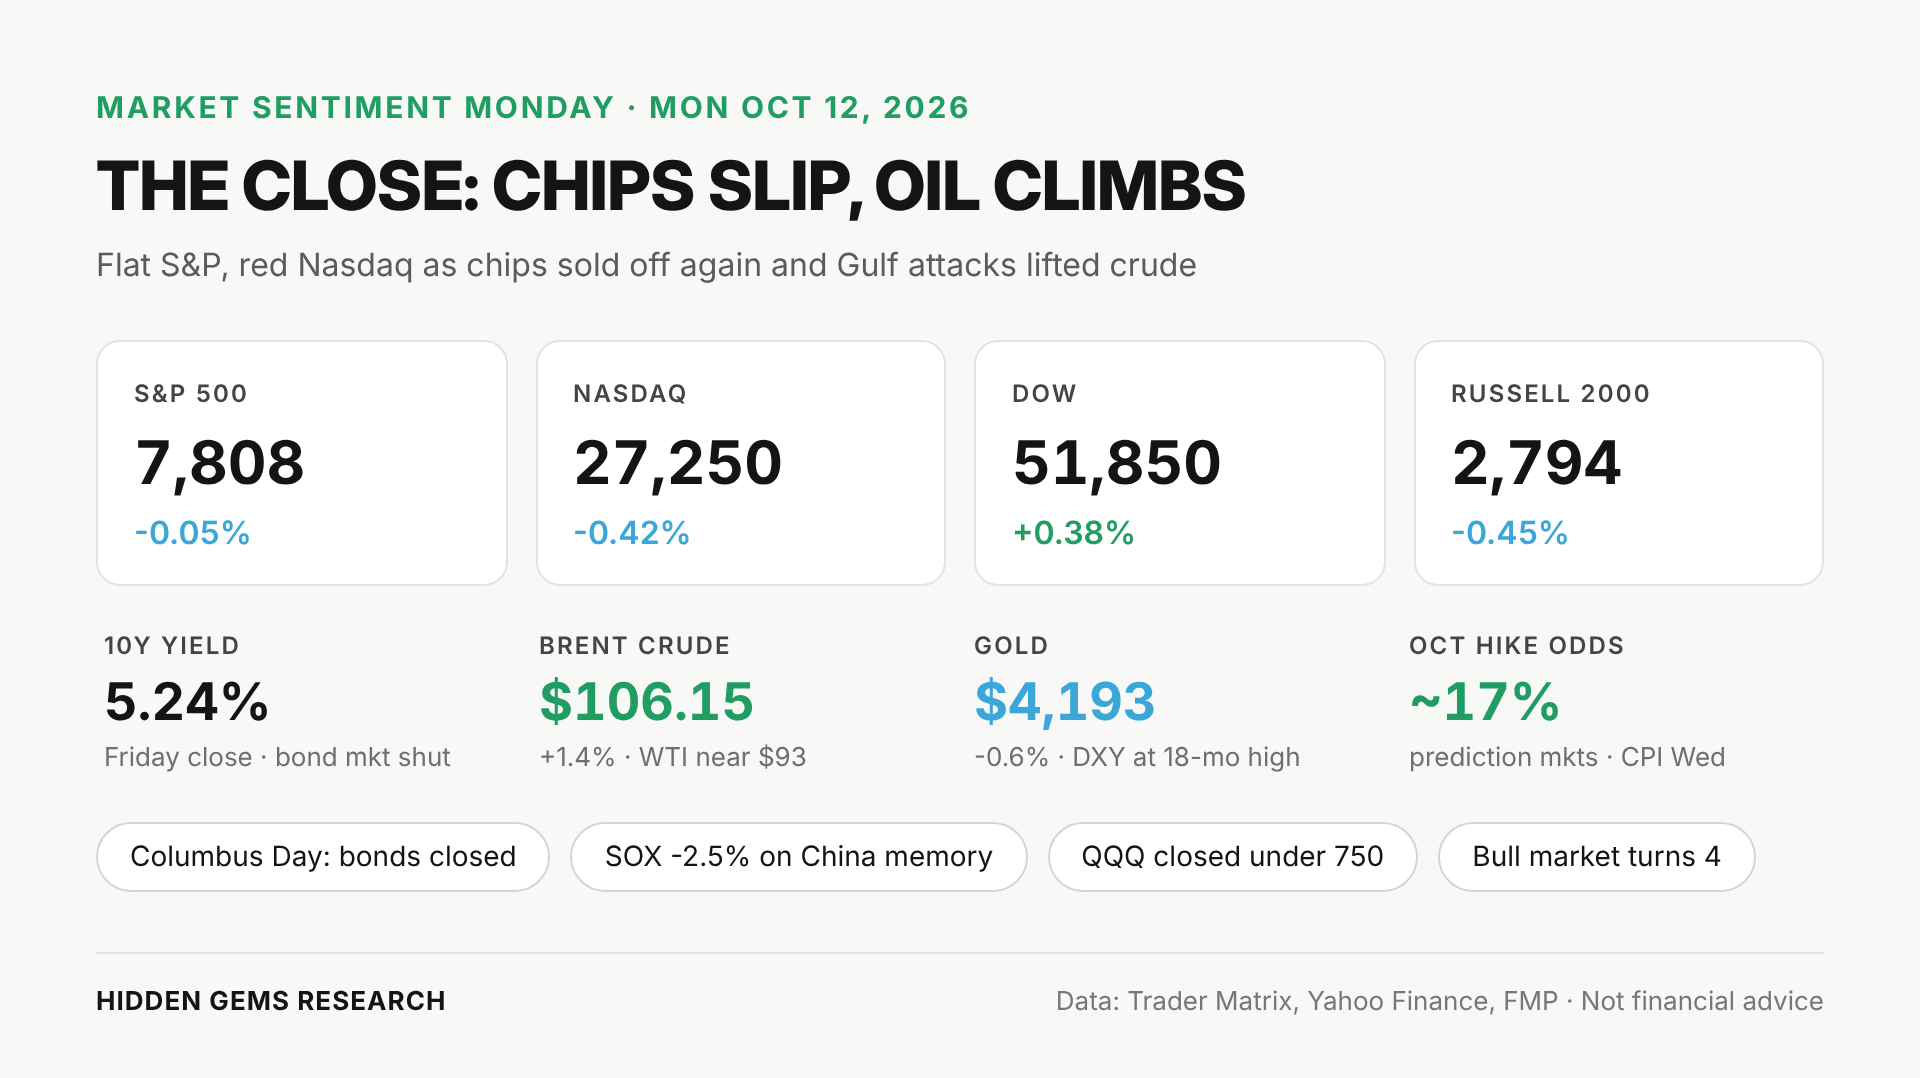
Its Monday so we are back at it again with another macro and HGR index specific update to let you know what’s happening in the market in one full-scope post! The bond market took Columbus Day off and stocks traded on thin rates liquidity today. The S&P 500 finished flat, down 0.05% at 7,808, and the Nasdaq gave back 0.42% to 27,250 as chip stocks sold off again. The Dow added 0.38% to 51,850 while the Russell 2000 lost 0.45%. The 10Y holds at Friday’s 5.24%. Brent climbed 1.4% to $106.15 after more Gulf attacks over the weekend, and the S&P bull market turned four today, up about 118% from the October 2022 low. Midterms are almost upon us and I expect volatility to stay heightened until after the polls are closed. Lets get into the full update!
THE PULSE
The S&P finished last week up 1.2% at 7,811.5, a hair under Tuesday’s record, while the Nasdaq lost 0.4% and the Russell 2000 dropped 1.4%. Thursday hurt most: an FT report put OpenAI’s annualized revenue about $20B below prior estimates, and ARM 0.00%↑ , INTC 0.00%↑ and, MRVL 0.00%↑ each fell more than 6%. Buyers reversed part of that Friday on reports of $70B+ in annualized revenue by year end. Sellers hit chips again today. The SOX traded down about 2.5% on worries about competition from China’s memory maker CXMT, and Broadcom CEO Hock Tan told investors some AI buyers are acting like casino gamblers who don’t know what they own. MSFT 0.00%↑ added pressure on the GPU trade when it unveiled Maia 300, its third in-house AI chip, and said Maia will now run most of its AI workloads, Copilot included. Microsoft hit a one-year high on the news.
Rates are staying pakred. Friday’s Treasury close left the 2Y up 3.5basis points at 4.79% and the 30Y flat at 5.60%, pricing more Fed tightening. Prediction markets put October hike odds near 17% after the payroll miss, with most of the money betting on December. Traders will reset those odds after Wednesday’s CPI. The dollar index hit its highest level since April 2025, and mortgage rates rose for a seventh straight week to 7.4%.
SECTOR ROTATION
Traders flipped last week’s chip trade. A week ago SMH 0.00%↑ led the board at +4.18 vs SPY. Over the last five sessions it trailed SPY by 5.48 points, the worst on the board, and XLK 0.00%↑ lagged by 1.68. Money moved into XLU 0.00%↑ (+2.81), IGV 0.00%↑ (+2.75), XLP 0.00%↑ (+2.44) and XLE 0.00%↑ (+2.44). It left SMH 0.00%↑ , XLK 0.00%↑ , XLI 0.00%↑ (-1.57) and ARKK 0.00%↑ (-1.39).
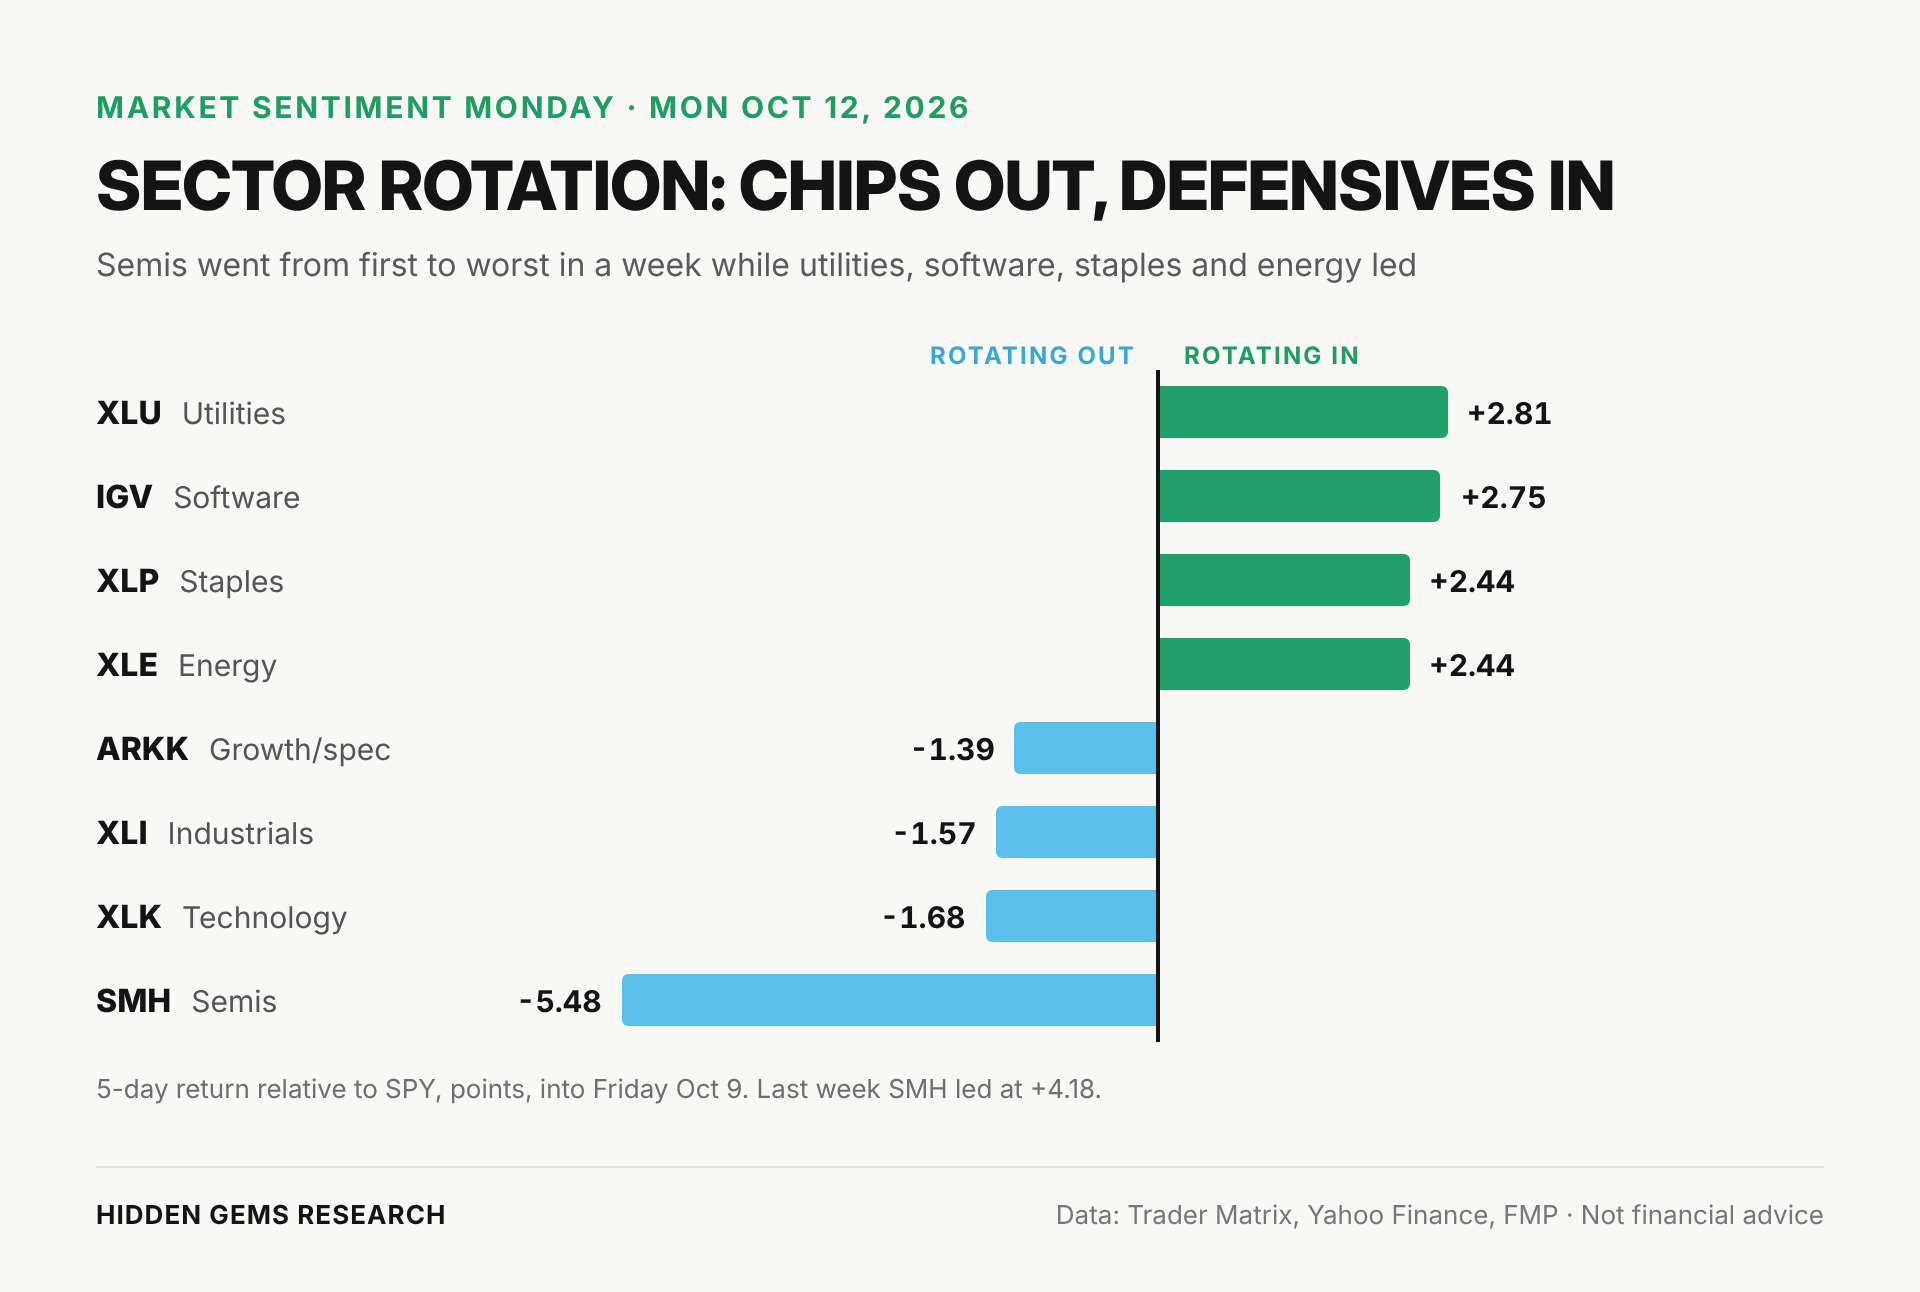
Watch the split inside tech. Software jumped 2.8% on Friday while semis fell 0.65%, so buyers moved AI money from the chipmakers up to the software layer and kept it in tech. Last Monday we flagged the 3.2x options surge in utilities. XLU then led the week. With defensives and energy on top, buyers are hedging inside an index that sits near records.
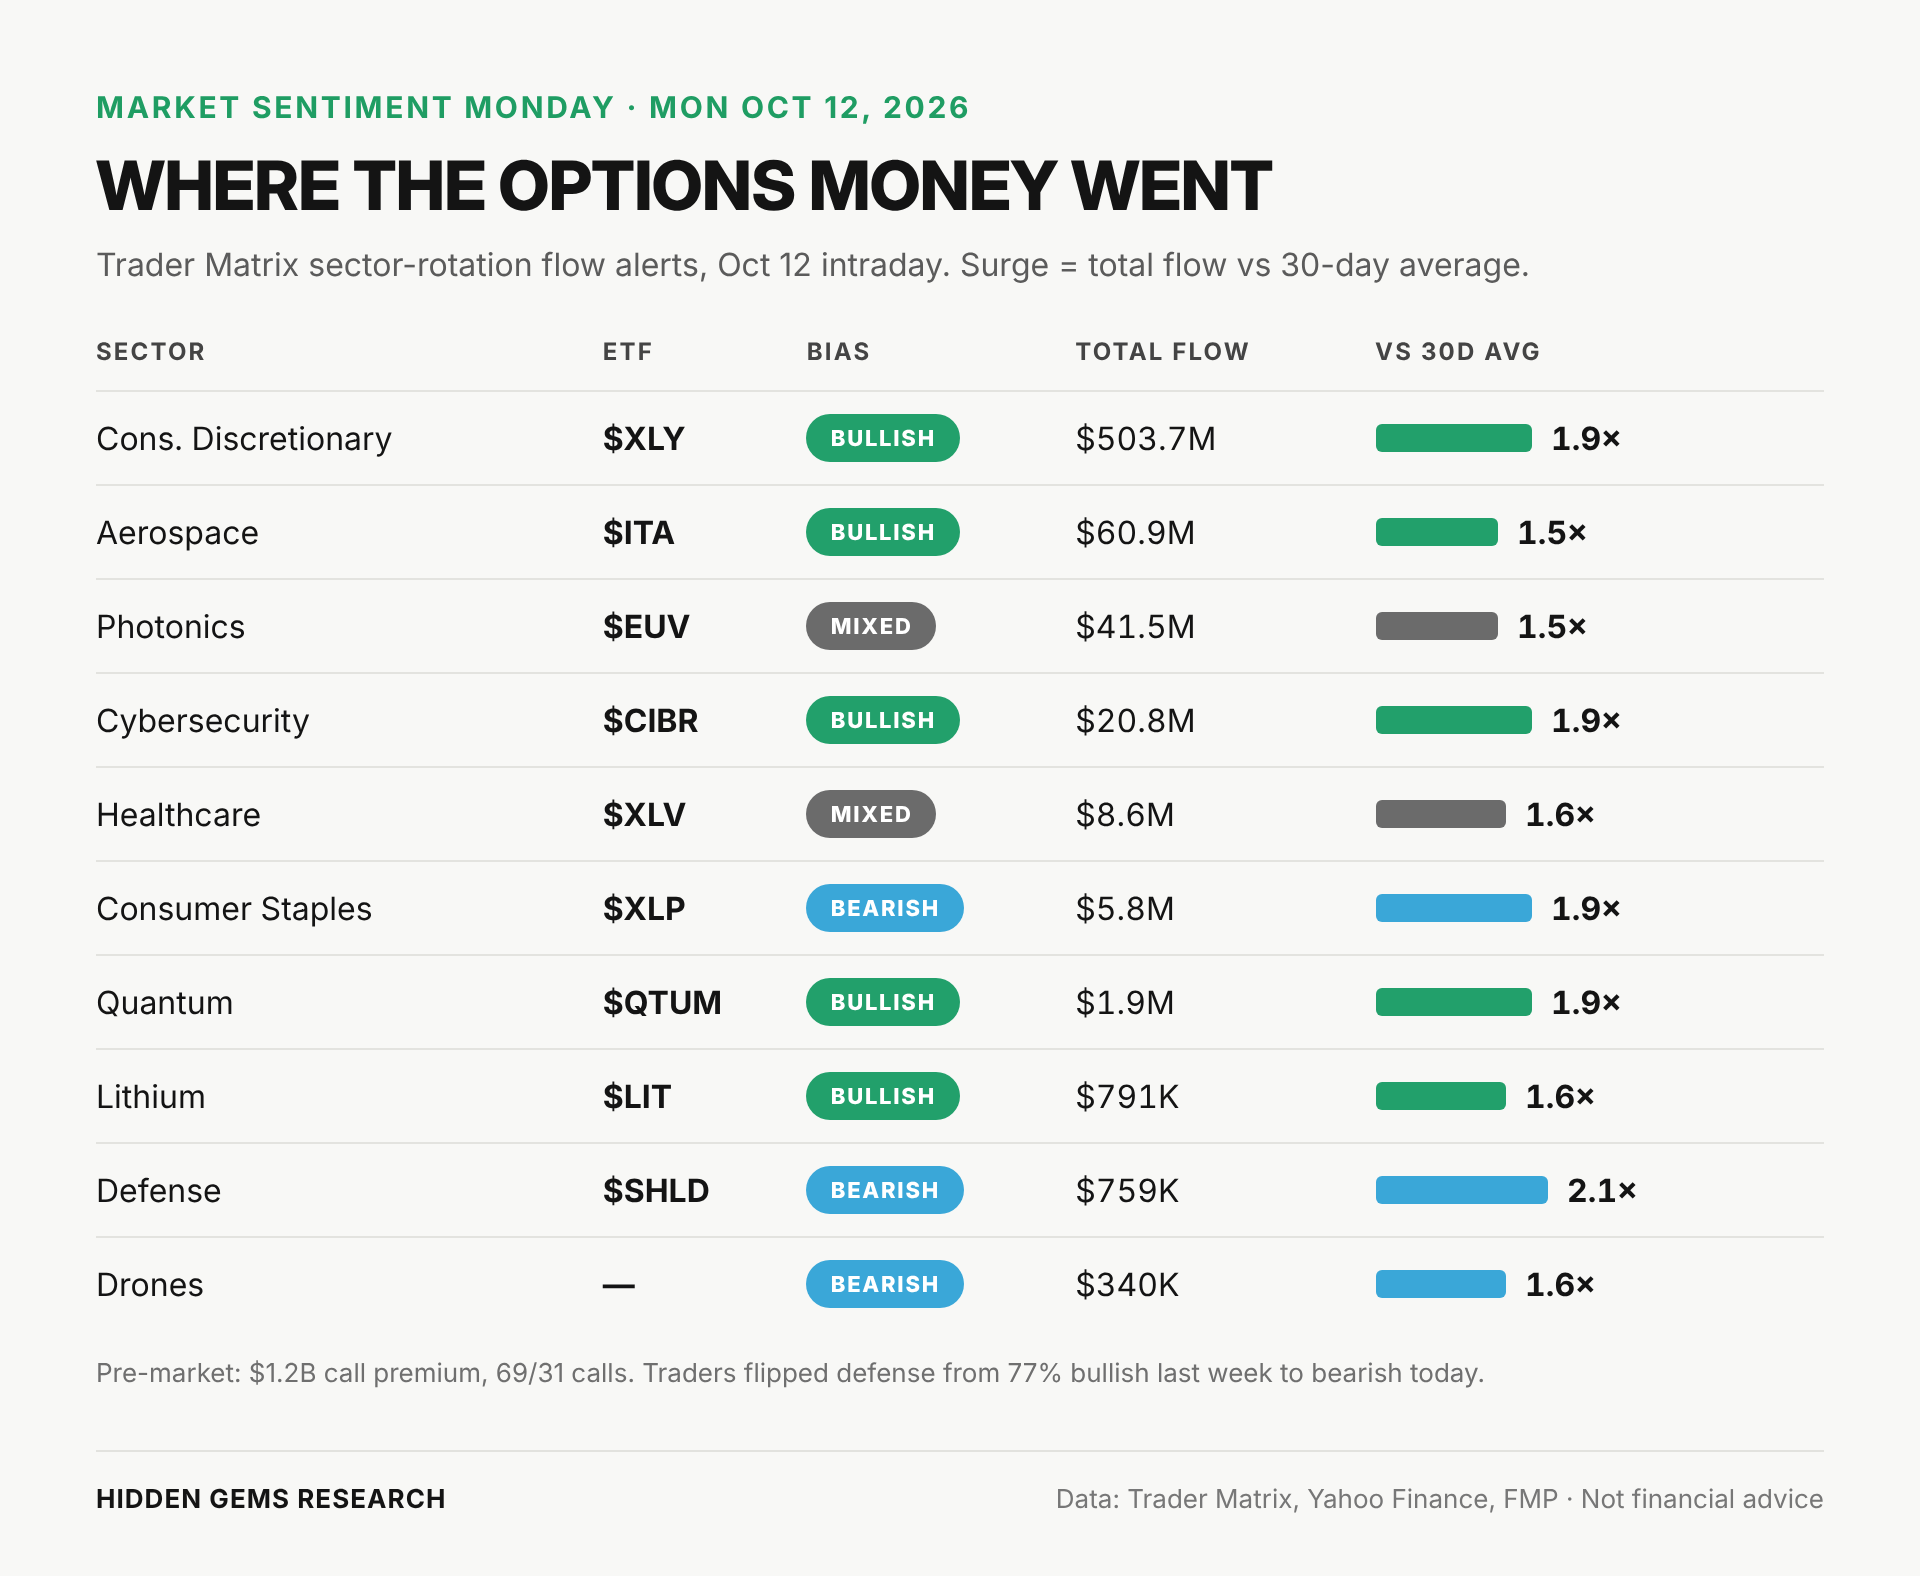
Options traders came in leaning bullish. Pre-market, call premium of $1.2B beat puts 69/31, and Trader Matrix counted 8 of 11 sectors bullish. Intraday flow alerts showed bullish surges in Consumer Discretionary (XLY, $503.7M at 1.9x its 30-day average), Aerospace (ITA, $60.9M at 1.5x), Cybersecurity (CIBR, $20.8M at 1.9x, $11.4M bullish vs $2.0M bearish), Quantum (QTUM, 1.9x) and Lithium (LIT, 1.6x).
MACRO AND GEOPOLITICS
Over the weekend, Houthi strikes on Riyadh’s King Khalid airport left a double-digit death toll, Saudi Arabia extended the airport closure, and Trump said the U.S. may join Saudi Arabia in striking the Houthis. This afternoon the Saudi-led coalition intercepted another Houthi ballistic missile over Riyadh after AFP reporters heard explosions in the city. Haaretz reported Netanyahu is asking U.S. mediators to secure Saudi permission for Israeli strikes on Houthi targets, and BBC reported Iran offered to broker Saudi-Houthi talks.
Attacks in Hormuz kept coming. UKMTO reported an unknown projectile hit an outbound products tanker in the strait today, with the crew safe, and Iran said a third crude supertanker caught fire there. Tehran said it will answer the U.S. response on its Hormuz proposal once its review finishes. Sixty nations signed a declaration opposing tolls and restrictions on international straits, and 29 countries, the U.S. and U.K. included, condemned Iran’s sabotage and cyber activity after London tied the IRGC to the September 27 plot at RAF Fairford.
Russia pulled oil the other way. Zelensky said Russia hit six Ukrainian energy facilities today, while Trump said both sides agreed to stop hitting energy infrastructure and Russia will ship diesel immediately. The EIA estimates that diesel covers nine days of U.S. demand. Traders sold ICE gasoil 3% on the truce headline, then bid Brent above $107 this morning anyway. China said it will work with Russia to protect key shipping routes, and North Korea fired two ballistic missiles over the weekend.
Central banks around the world keep hiking. Fifteen of 33 major central banks have hiked in the last six months, India’s RBI raised rates on October 7 for the first time in nearly four years, and India’s 10Y hit a three-year high. Citi expects Treasury Secretary Bessent to shrink long-bond auctions and possibly cancel 20-year sales, which would take some supply pressure off the long end that drove last week’s selloff. Investors put a record $30.7B into gold ETFs in Q3.
For the full brief and specific trade set ups in the 30+ Stock HGR Watchlist become a premium member today! All Sector and Option Data is provided by Trader Matrix, try it here!
