

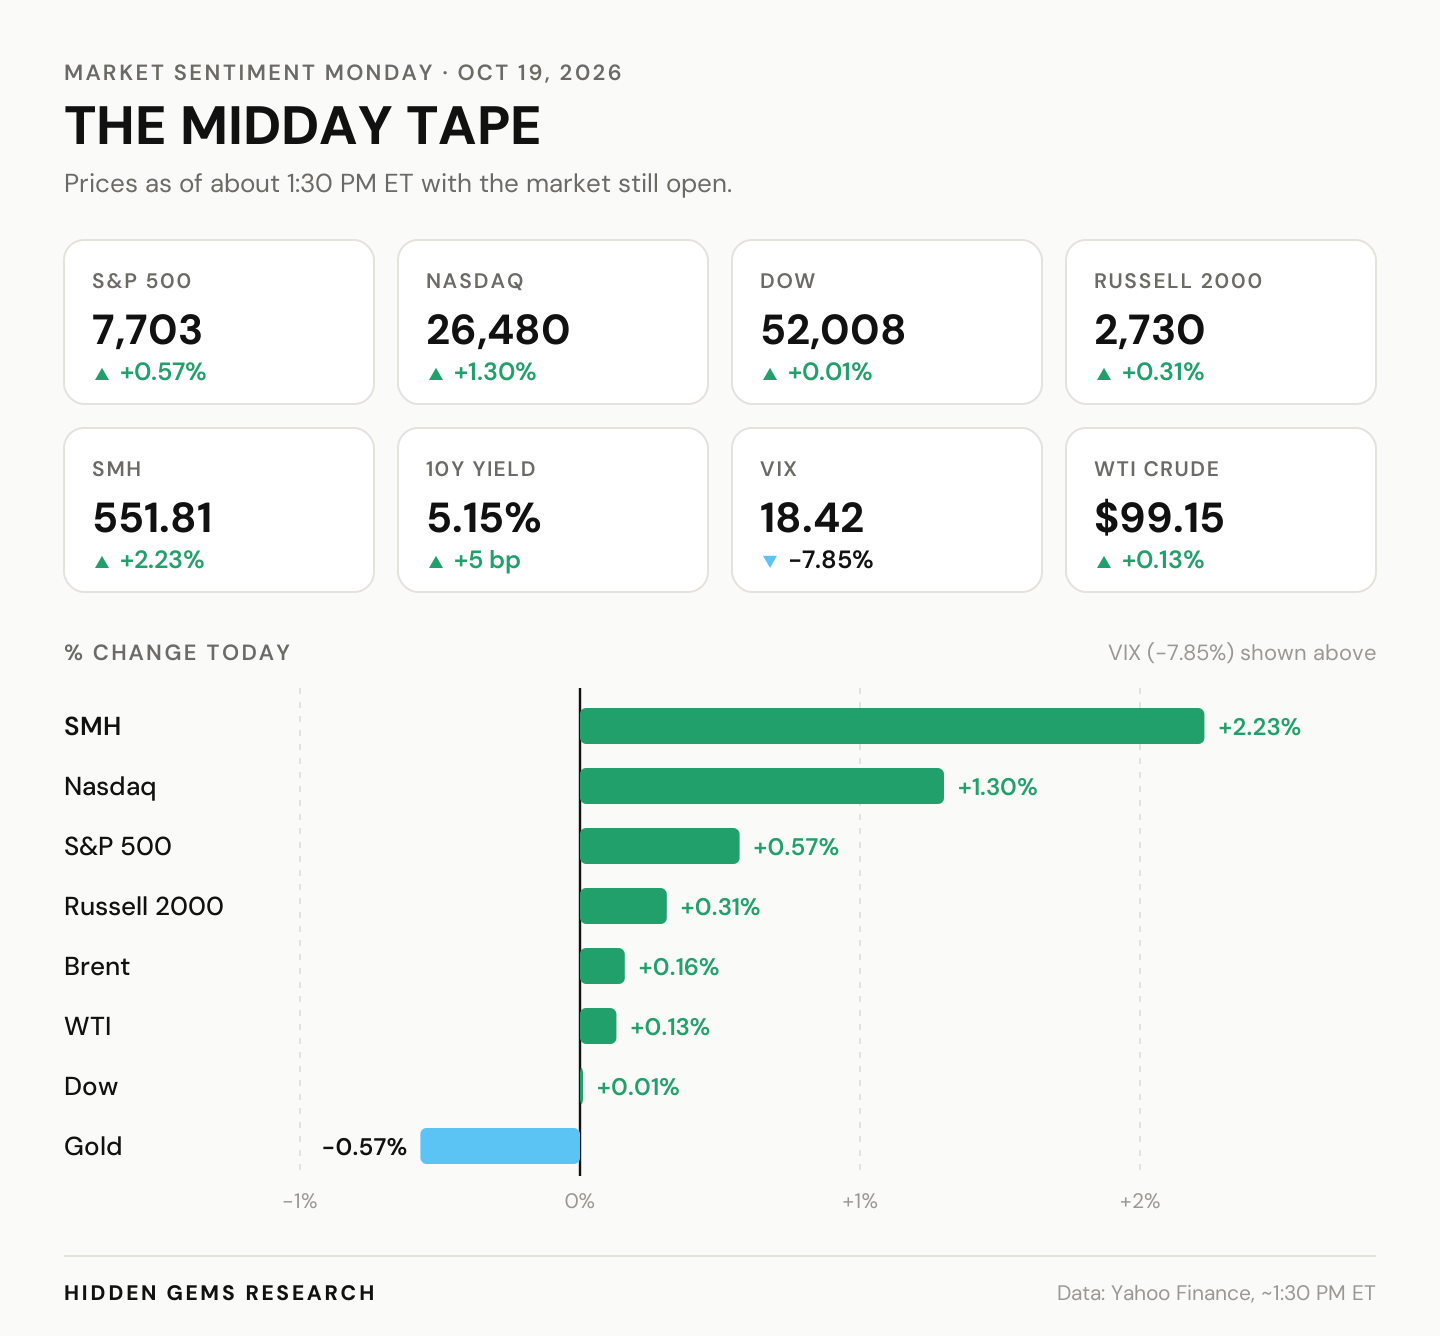
Chips are bouncing today, and I’m watching to see whether the bounce holds. There are some serious cracks in the market due to the global oil crisis and I'm not ready to go full bull just yet after what happened last week. As of 1:30 PM ET, the Nasdaq is up 1.3% at 26,480 and SMH is up 2.2%. The SOX is on pace to snap an eight-session losing streak, its longest since 2008. The S&P 500 is up 0.57% at 7,703, the Russell 2000 is up 0.31% and the Dow is flat at 52,008. The 10Y is up about 5 basis points to 5.15%, and VIX is down 7.9% to 18.4.
THE PULSE
Last week hurt. On Friday the Nasdaq fell 2.1% and the S&P lost 1.1%, the worst day of the week for tech. The SOX dropped 3.8% for its eighth straight loss and finished the week down 11.4%. Traders blamed Chinese chip competition and debt-funded AI buildouts, with CoreWeave’s debt load as the poster child. The Nasdaq sat at 27,250 last Monday. It’s at 26,480 now, even with today’s rally.
Today buyers are stepping back in. Morgan Stanley named Amazon its top pick and raised its target to $350, and AMZN is up 5%, adding about $135B in market value. JPMorgan upgraded Intel, and memory names led the early chip bounce, with SanDisk up 7.4% and Micron up 4.7% by late morning.
I’m not calling a bottom yet. The Dow is flat while the Nasdaq rallies, and I think we are sitting on what good be a relief bid and bull trap. Global tech funds we track lost $4.8B in the week ending October 14, with U.S. tech funds losing $5.2B on their own. All equity funds took in $20B over the same week. Investors pulled money out of tech and put it into the rest of the market. Goldman’s sentiment indicator fell to the 46th percentile, its lowest reading since April. The entire market had a much larger figure erased from the market that starts with a “T”. Scary stuff, but fear leads to opportunity in my eyes which we will look into later.
Bonds aren’t helping the bulls. The 2Y sat at 4.75% and the 30Y at 5.44% this morning, and the 10Y has climbed to 5.15% since. Last week’s inflation data ran hot: CPI at 3.7% year over year, PPI up 1.3% month over month and 6.3% year over year, and import prices up 1.1% in September. Fed Chair Warsh said Friday he won’t prejudge upcoming meetings, and the Fed is now in its pre-meeting blackout. Traders expect a hold on October 28, but they haven’t ruled out a hike. This morning homebuilder confidence fell to a 14-year low, and real estate is one of the weakest sectors so far today.
Buyers moved the Trader Matrix gamma map today. SPY and QQQ both opened below their near-term gamma flips, which put dealers short gamma. SPY started the day near 763 against a 767 flip, and QQQ started near 710 against a 717 flip. Buyers pushed both through. SPY is at 767.64, above its flip, after tagging 770.46 at the 770 call wall. QQQ is at 720.08 after topping out at 724.55, 45 cents under its 725 call wall. Above the flip, dealers sell rips and buy dips, which pins the tape between the walls. If SPY slips back under 767 into the close, the 755 put wall comes back into play. The structural flips sit higher, near 771 for SPY and 730 for QQQ, so dealers stay short gamma on longer-dated options even if buyers close the day strong.
SECTOR ROTATION
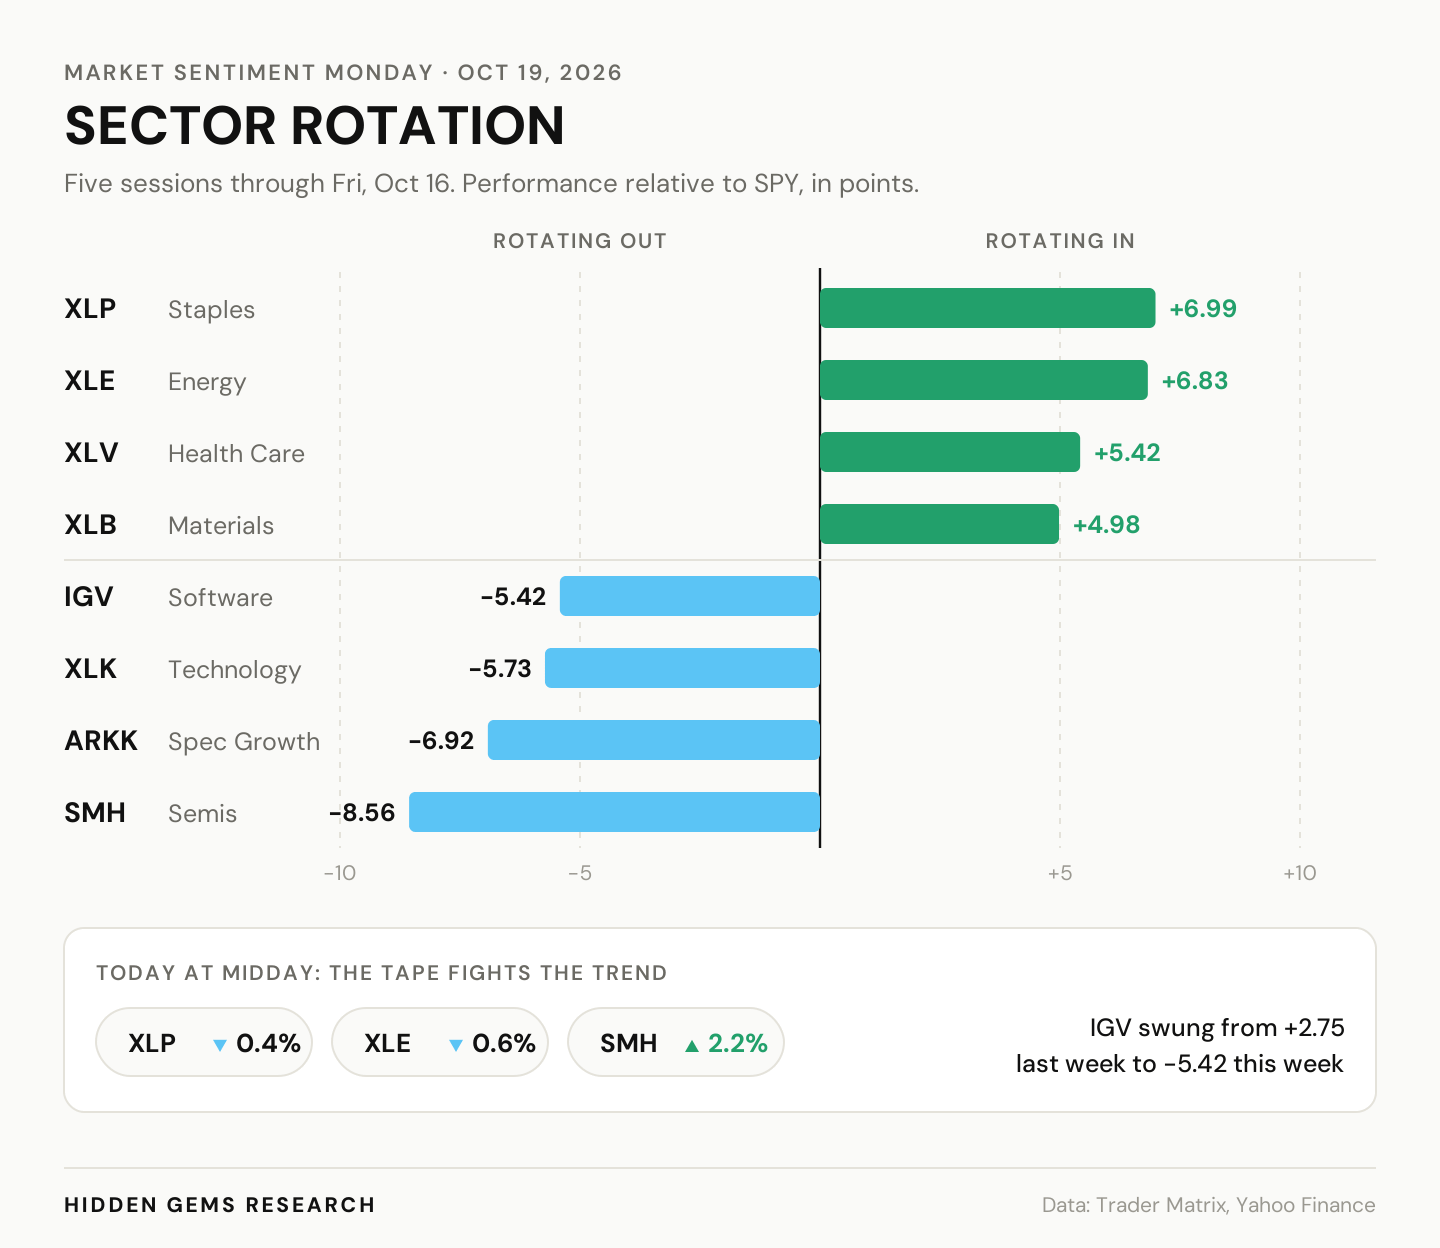
Over the five sessions through Friday, money went into XLP (+6.99 vs SPY), XLE (+6.83), XLV (+5.42) and XLB (+4.98). It came out of SMH (-8.56), ARKK (-6.92), XLK (-5.73) and IGV (-5.42). Staples beat semis by more than 15 points in one week. SMH has now been the worst on the board two weeks running. Last week I said buyers were moving AI money from chips up to software. This week they sold both, and IGV swung from +2.75 to -5.42. Today buyers are fighting that trend. At midday XLP is down 0.4% and XLE is down 0.6% while SMH is up 2.2%.
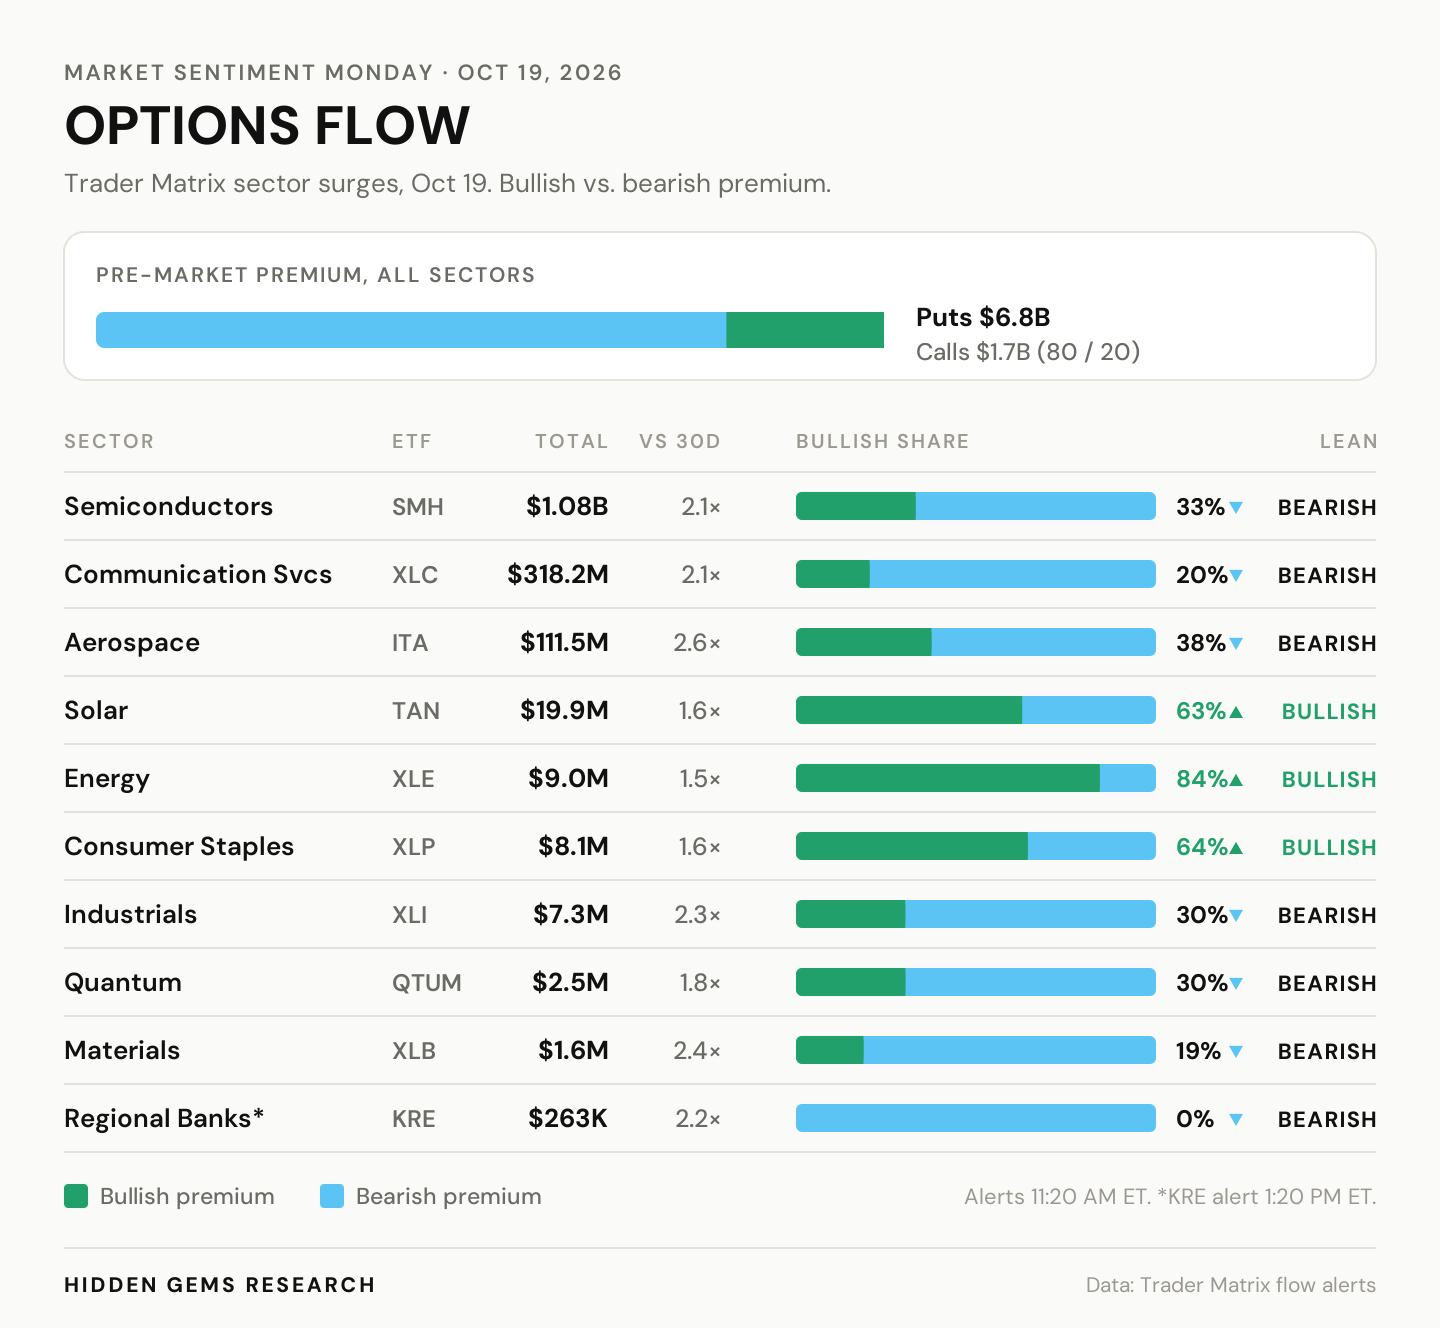
Options traders aren’t buying the bounce. Pre-market, puts outweighed calls $6.8B to $1.7B, with heavy bearish flow in Tech and Consumer Discretionary. At 11:20 AM ET, Trader Matrix flagged a bearish surge in Semiconductors: $1.08B in total flow at 2.1x its 30-day average, with $440.9M bearish against $219.5M bullish. Communication Services drew $318.2M at 2.1x, $177.9M bearish against $45.7M bullish, two days before Meta reports. Aerospace (ITA) drew $111.5M at 2.6x, $26.2M bearish against $15.8M bullish, a full reversal of last Monday’s bullish ITA surge. Industrials (XLI, 2.3x), Materials (XLB, 2.4x) and Quantum (QTUM, 1.8x) came in bearish too, and Regional Banks (KRE) joined them at 1:20 PM ET.
The bullish surges went to Energy (XLE, $5.4M bullish vs $1.0M bearish at 1.5x), Consumer Staples (XLP, $4.7M vs $2.6M at 1.6x) and Solar (TAN, $7.6M vs $4.5M at 1.6x). Last Monday traders bought XLP puts, betting the defensive bid had run far enough. XLP then beat SPY by 7 points. Today they’re back on the call side.
Put the price and the flow side by side. Buyers are lifting chips on the tape, while options traders use the bounce to buy protection and keep paying up for defensives and energy. Until semis flow turns bullish, I treat today’s rally as short covering into big-tech earnings.
MACRO AND GEOPOLITICS
Oil traders had two stories to price today. On Friday, Trump waived the new Graham Act sanctions and tariffs on Russia while leaving older sanctions in place, which opens a path to more Russian fuel. WTI fell 3.7% pre-market to $97.67 on that, and today Trump said he cut a diesel export deal with Russia and delayed further sanctions. Then, around midday ET, an Iranian Navy spokesman told Al Jazeera that two projectiles fired by U.S. forces hit a 35mm cannon at Konarak Naval Base overnight and injured two Iranian sailors. CENTCOM has not confirmed it. If it holds up, it’s the first U.S. strike on Iranian soil since September 1, and an IRGC response is possible. Traders erased crude’s Russia drop. WTI is at $99.15, flat on the day after a $96.72 low, and Brent is at $110.04 after trading as low as $106.82.
Houthi spokesman Yahya Sarea announced a wide wave of attacks on Saudi targets: Aramco facilities in Yanbu, the Shaybah oil field, King Khalid airport in Riyadh, Abha airport, the Khamis Mushait air base, the Jazan naval base and the Bir Askar radar near Najran. He called it retaliation for Saudi strikes in Yemen. Those are Houthi claims for now. Hormuz is still shut, Iran says its seven-day reopening offer still stands, and an Emirati government delegation flew back into Tehran today.
French authorities imposed a curfew on parts of central Paris, including Place de la République and Les Halles, after violent protests. Investors are selling European stocks, bonds and the euro as unrest spreads through France and Italy. Back home, Treasury Secretary Bessent tied September’s inflation to an energy shock.
For the full brief and specific trade set ups in the 30+ Stock HGR Watchlist become a premium member today! All Sector and Option Data is provided by our friends at Trader Matrix, try it here!
